Buying a home in Fort Lauderdale means navigating flood zones, windstorm insurance, HOA documents, condo association rules, and a seller pool that expects financially prepared offers, and the numbers reflect just how active this market remains. The median sale price sits around $580,000 as of mid-2026, with active listings concentrated between $500,000 and $1 million, and neighborhoods like Victoria Park, Rio Vista and Coral Ridge pushing well beyond that. Many buyers consider Fort Lauderdale one of the most sought-after markets in South Florida, and the pace of activity in desirable neighborhoods makes it easy to see why.
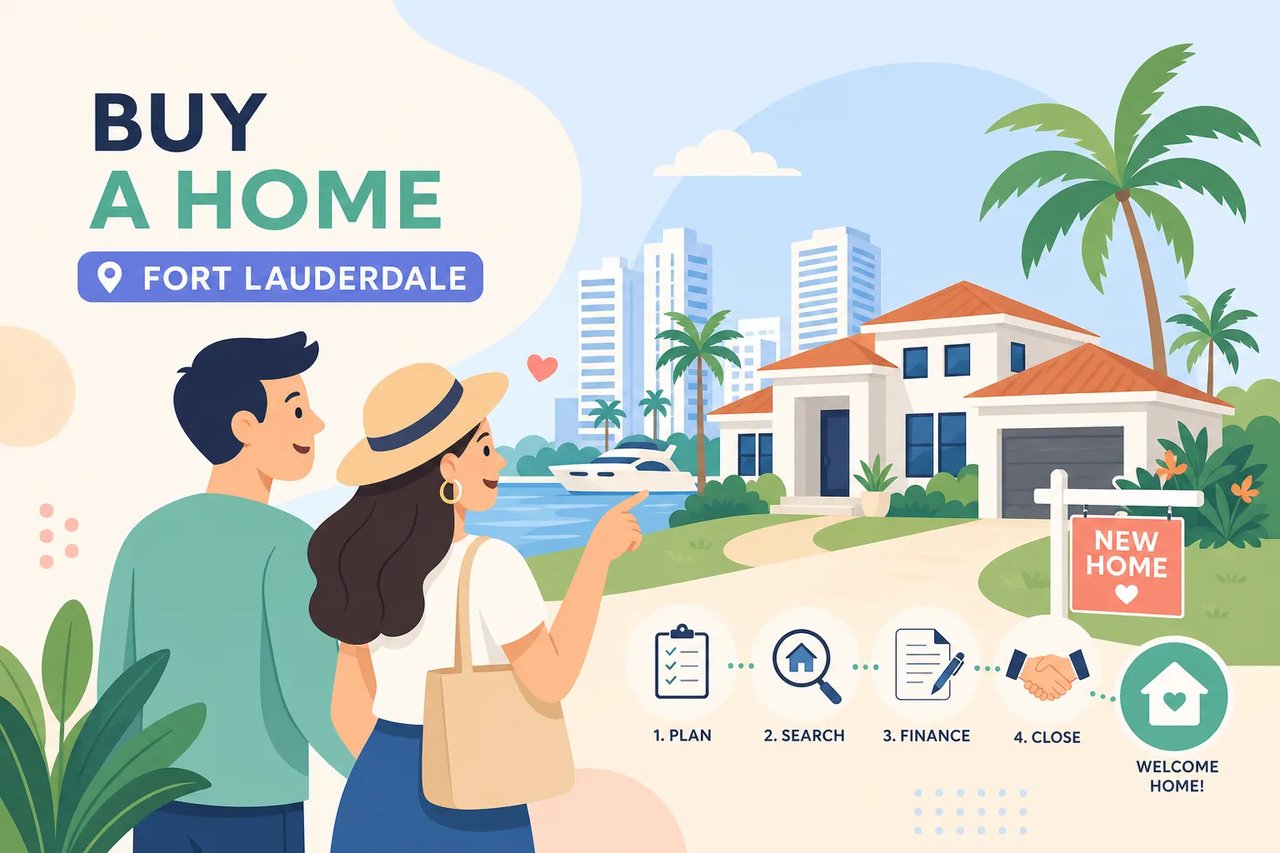
That doesn't mean the process is out of reach. Going in with a clear roadmap is what separates buyers who close on the right home from those who spin their wheels for six months. At Greg Pereira Real Estate, buyer conversations follow a consistent sequence: financial preparation, neighborhood clarity, market awareness, true cost budgeting, offer strategy, and a guided path to closing. Follow these steps and the process becomes manageable at every stage.
1. Get financially ready before buying a home in Fort Lauderdale
Pre-approval isn't a formality in Fort Lauderdale. It's a competitive requirement. With roughly 2,000+ active citywide listings as of September 2026, an offer without a solid pre-approval letter commonly doesn't receive serious consideration in competitive situations, especially for well-priced homes that have already fielded multiple inquiries. You want to be in a position to move within days of finding the right property, not weeks.
Lenders will review your credit score, debt-to-income ratio, employment history, and cash reserves. Many lenders begin offering broader loan pricing and product access at credit scores near 680, and most conventional lenders want to see your DTI below 43%. Have two years of tax returns, recent pay stubs, and bank statements ready before you sit down with a lender.
How much cash do you actually need at the start
Think of your upfront cash in three separate buckets. The first is your down payment: on a $580,000 home, a 5% down payment is $29,000 and a 20% down payment is $116,000. The second is closing costs, which typically run 2% to 5% of the purchase price in Florida, adding roughly $11,600 to $29,000 to your out-of-pocket total. The third is earnest money, a good-faith deposit that goes into escrow at contract and commonly falls in the range of 1% to 3% of the purchase price in South Florida.
Florida also offers first-time buyer assistance programs worth knowing. The statewide Hometown Heroes program offers up to $35,000 for eligible essential workers, while FL Assist provides up to $10,000 as a deferred second mortgage with no monthly payments. Income limits and credit thresholds apply, but for buyers who qualify, these programs can meaningfully reduce the cash needed upfront.
2. Choosing the right Fort Lauderdale neighborhood for your lifestyle
Fort Lauderdale isn't one market. It's a collection of distinct neighborhoods, each with its own personality, price point, and lifestyle fit. Choosing the right area before you start touring saves weeks of wasted searches and prevents buyers from falling in love with a home that doesn't match how they actually live. A knowledgeable local agent can tell you which blocks are appreciating, which HOAs are financially healthy, and which streets flood after heavy rain, details that never appear in a public listing.
Best neighborhoods for families and everyday livability
Imperial Point offers a suburban feel with strong school access and a median sales price around $772,000, making it one of the more established family neighborhoods in the city. Tarpon River and Sailboat Bend both offer good commuter access to downtown Fort Lauderdale without the premium pricing of neighborhoods east of Federal Highway (US-1).
Best areas for commuters who want walkability and central access
Victoria Park is one of the most walkable neighborhoods in Fort Lauderdale, positioned within easy reach of Las Olas Boulevard and downtown. Median prices here range from around $650,000 into the $1 million-plus range depending on the sub-area and property type. Rio Vista sits centrally and offers waterfront pockets alongside strong value retention, though prices vary considerably based on whether a property has Intracoastal or canal access.
Beachfront and Intracoastal living: what buyers should know
Central Beach, Harbor Beach, Las Olas Isles and Coral Ridge are the primary targets for buyers who want direct or close ocean access. Beachfront neighborhoods carry significantly higher insurance costs, which is covered in detail in the next section and deserves serious attention before you fall in love with an oceanside address.
3. Finding Fort Lauderdale homes for sale and reading the 2026 market
The most reliable way to access current Fort Lauderdale property listings is through the MLS, either directly through a licensed agent or via connected consumer platforms. Public sites like Zillow and Realtor.com pull from MLS data but can lag by 24 to 48 hours on status changes. In a market where well-priced homes in desirable neighborhoods can go under contract within days of listing, that lag matters. A local agent also has visibility into off-market conversations and pocket listings that never appear publicly.
What the 2026 Fort Lauderdale home market actually looks like
The market has shifted meaningfully from the 2022 to 2023 peak. Single-family homes are averaging 122 days on market with 796 active listings citywide, while condos/townhouses are averaging 152 days on market with 1343 active listings. The citywide median sale price sits around $580,000, with active listing prices closer to $699,000. That gap between list and sale price signals negotiating room in many situations, though desirable properties in tight neighborhoods are still attracting competitive offers.
Mortgage rates in September 2026 are running approximately 6.8% for a 30-year fixed loan, which affects purchasing power significantly compared to the low-rate environment of 2020 and 2021. Budget your monthly payment calculations using the current rate environment, not historical rates you may have seen referenced in older articles.
Single-family homes vs. condos: which makes sense for you
Fort Lauderdale condos for sale come with a layer of complexity that single-family homes don't carry. Condo association rules govern rentals, renovations, pet policies, and resale requirements, and the financial health of the association directly affects your investment. Before going under contract on any condo, review the association's financials, reserve fund status, and meeting minutes for the past two years. Average condo HOA fees in Fort Lauderdale run approximately $620 to $646 per month in 2026, with luxury and high-rise buildings running substantially higher.
4. The real cost of buying a home in Fort Lauderdale
Most buyers calculate their mortgage payment and stop there. In Fort Lauderdale, that's a significant budgeting mistake. The true monthly cost of ownership includes property taxes, homeowners insurance, windstorm coverage, flood insurance, and HOA fees, and in South Florida, those numbers add up fast.
Property taxes: what to expect in Broward County
Fort Lauderdale property taxes generally run around 2% of the assessed value annually. On a $500,000 home, plan for approximately $9,000 per year. On a $1 million home, budget $20,000 annually. Florida's Homestead Exemption reduces the taxable value of a primary residence by up to $50,000 and caps annual assessment increases at 3%, so buyers who intend to live in the home should apply as soon as the sale closes.
Insurance in South Florida: the number that surprises most buyers
Fort Lauderdale sits across multiple FEMA flood zones: AE, VE, AH, and X. Each carries different risk levels and premium implications. Beachfront properties in VE zones, the coastal high-hazard zone with wave action, cost even more.
Even X-zone properties, which sit outside the high-risk floodplain, often carry voluntary flood insurance because South Florida's drainage and storm surge patterns make the coverage worth it. Hurricane mitigation upgrades, impact windows, roof reinforcement, and storm shutters, can reduce windstorm premiums meaningfully but require upfront investment. Request a wind mitigation inspection as part of your due diligence; the savings over time can more than offset the inspection cost.
HOA and condo fees: know the full picture before you make an offer
HOA fees for single-family homes vary widely based on community amenities and the size of the reserve fund. Condo associations often bundle building insurance within the monthly fee, but buyers must verify exactly what is and isn't covered, because the line between the association's policy and your individual unit coverage isn't always obvious. Reviewing the association's financials is as important as reviewing the property itself, particularly in older buildings where deferred maintenance or underfunded reserves can lead to special assessments after you've already closed.
5. Writing an offer that actually wins
With single-family homes averaging 122 days on market in Fort Lauderdale, buyers have more negotiating room than they did two years ago. That doesn't mean every offer wins on price alone. Sellers still evaluate the terms, contingencies, and credibility of the buyer, and a well-structured offer from a prepared buyer regularly outperforms a slightly higher number wrapped in conditions that create risk for the seller.
How to price your offer using comparable sales
The list price is a starting point, not a directive. Your agent should pull recent comparable sales, filtered by price per square foot, property type, neighborhood sub-area, and days on market, to anchor your offer to actual market data. In neighborhoods like Victoria Park, Rio Vista, and Coral Ridge where price variability is high, relying on public estimate tools without MLS data can lead to significant overbidding or an offer the seller won't take seriously.
Contingencies that protect you without killing the deal
An inspection contingency is standard and non-negotiable for Fort Lauderdale homes, especially those older than 20 years with hurricane exposure history. An appraisal contingency protects financed buyers from overpaying if the lender's appraisal comes in below the contract price. A financing contingency gives you an exit if your mortgage doesn't come through. Waiving contingencies is sometimes appropriate in cash offers on well-priced properties, but that's a conversation to have with your agent based on specific circumstances, not a blanket strategy.
Earnest money and what sellers expect in South Florida
Earnest money in Fort Lauderdale commonly falls in the range of 1% to 3% of the purchase price and is typically deposited into escrow within a few business days of an accepted contract, though exact timing is governed by the contract terms, so confirm the deadline with your agent. On a $580,000 home, that's $5,800 to $17,400 held in a third-party escrow account. If you exit the contract within a properly exercised contingency period, the earnest money generally returns to you. If you walk away without a valid contingency reason, the seller may be entitled to keep it, though outcomes can vary depending on contract language, so review the terms carefully with your agent and, if needed, a Florida real estate attorney.
6. From accepted offer to closing day: what happens next
Once an offer is accepted, the clock starts on a defined sequence of tasks. In Florida, a financed purchase typically closes in 30 to 45 days. FHA and VA loans often run 40 to 60 days due to additional appraisal and underwriting steps. Cash purchases can close in 7 to 21 days depending on title turnaround. Staying ahead of each milestone is where having a hands-on agent makes the process feel controlled rather than chaotic.
The home inspection: what Fort Lauderdale buyers should look for
Schedule a general inspection plus roof, electrical, plumbing, and HVAC inspections early in your contingency period, most buyers aim for the first week after contract to leave time for review and renegotiation before deadlines hit. Add a wind mitigation inspection to the list: it generates a report that can qualify you for windstorm insurance discounts and is worth the $150 to $200 fee. In South Florida, pay specific attention to roof age, hurricane strap installation, signs of water intrusion, cast iron plumbing and older electrical panels. These five items are the most common sources of post-inspection renegotiation and, in some cases, reasons to walk away.
Appraisal, title search, and lender conditions
Your lender will order an independent appraisal to confirm the property's value supports the loan amount. Simultaneously, a title company conducts a title search to uncover any liens, encumbrances, or unresolved ownership disputes. Title insurance protects you and the lender going forward. Once the lender issues a clear-to-close, all conditions have been satisfied and the closing can be scheduled.
What to expect on closing day in Florida
Review your Closing Disclosure at least three business days before closing and compare every line to your original Loan Estimate. Bring a cashier's check or confirm a wire transfer for your remaining down payment and closing costs. The final walkthrough happens 24 to 48 hours before closing to confirm the property's condition matches what you agreed to purchase. Once documents are signed and funds are disbursed, the keys are yours.
FAQs about buying a home in Fort Lauderdale
How long does it take to buy a home in Fort Lauderdale?
From the start of your home search to closing, most financed purchases take 60 to 90 days, roughly 30 days to find a property and get an offer accepted, followed by a 30 to 45 day closing period. Cash buyers can move faster, sometimes closing in as little as three to four weeks total.
Do I need flood insurance when buying a home in Fort Lauderdale?
It depends on the flood zone. Homes in FEMA-designated high-risk zones (AE, VE, AH) typically require flood insurance as a condition of the mortgage. Properties in X zones aren't required to carry it, but many South Florida buyers choose to given the region's drainage patterns and storm surge history.
What is the best neighborhood in Fort Lauderdale for first-time buyers?
South Middle River, Middle River Terrace and Riverland offer more affordable pricing with solid access to downtown, making them among the more attainable entry points in the city. The right neighborhood ultimately depends on your commute needs, lifestyle, and budget, a conversation worth having with a local agent before you start scheduling tours.
You now have a complete roadmap: use it
Buying a home in Fort Lauderdale is achievable when you understand what each stage requires. Get financially ready first. Choose your neighborhood based on lifestyle, not just price. Understand what the 2026 market is actually doing. Budget for the real cost of South Florida ownership, taxes, insurance, and HOA included. Write a structured offer with the right contingencies. Then execute each step between contract and closing without letting anything slip.
Every buyer Greg Pereira works with gets the same concierge-level attention: neighborhood guidance tailored to how they actually live, offer strategy built on real MLS data, and consistent communication from the first conversation through closing day. You work directly with Greg, not passed to an assistant, and that continuity matters when timelines tighten and decisions need to be made quickly.
If you're ready to start or still in the early research phase, reach out to Greg Pereira for a no-pressure conversation. Whether you're targeting your first home in Tarpon River, a waterfront property in Rio Vista, or a beachfront condo on Fort Lauderdale Beach, the right guidance from the start makes every step after it easier.